Kenyan Banks Lose Record Sh1.9 Billion to Fraud as CBK Raises Alarm
NAIROBI, November 6, 2026 — Kenya’s banking sector lost KSh 1.904 billion to fraud in 2025, up from KSh 1.594 billion a year earlier, according to the Central Bank of Kenya’s (CBK) Kenya Financial Sector Stability Report, published by CBK on November 3, 2026.
The 19.4 percent increase came as reported fraud cases rose from 353 in 2024 to 385 in 2025. The figures refer to reported banking-sector losses; the report does not establish that customers personally bore the entire amount.
Card fraud overtakes mobile banking losses
Card fraud caused KSh 645.2 million in losses in 2025, up from KSh 263.3 million in 2024, despite reported cases dropping from 24 to 16. Mobile banking fraud accounted for KSh 634.3 million, down from KSh 810.7 million the previous year.
The shift is important: the largest losses did not necessarily occur in the category with the most reported cases. It also underscores the need for banks to evaluate the financial severity of incidents, not only their frequency.
CBK breakdown of fraud losses in 2025
| Type of fraud | Actual loss in 2025 |
|---|---|
| Card fraud | KSh 645.2 million |
| Mobile banking fraud | KSh 634.3 million |
| Computer fraud | KSh 212.5 million |
| Identity theft | KSh 168.2 million |
| Online banking fraud | KSh 157.5 million |
| Internet scams | KSh 86.5 million |
| Total | KSh 1.904 billion |
Source: CBK Financial Sector Stability Report 2025, Table 14, page 78. Amounts rounded.
Online banking fraud cases increased from 106 to 132, with losses rising from KSh 111.8 million to KSh 157.5 million. Reported internet scams jumped from nine to 22, while losses climbed from approximately KSh 6.1 million to KSh 86.5 million. Identity-theft cases rose to 63 from 56, although recorded losses declined to KSh 168.2 million.
How much was exposed to fraud?
CBK recorded KSh 2.031 billion in amounts exposed to fraud in 2025, against KSh 1.904 billion in actual losses. The difference, approximately KSh 127.4 million, represents exposure that did not translate into recorded losses; it should not automatically be described as money recovered, because the report’s table does not provide a separate recovery figure.
Compared with 2024, the value exposed to fraud increased modestly while actual losses climbed much faster. This suggests the banking system recorded a higher proportion of exposed funds as losses.
Why the figures matter for Kenyan bank customers
Digital financial services have made it easier to transfer money, pay bills and manage accounts. But the growth of online services also creates more opportunities for account compromise, fraudulent payment instructions and identity-related scams.
CBK identifies cyberattacks and operational vulnerabilities as continuing risks to financial stability. Banks need effective monitoring, stronger access controls and rapid incident response, while customers benefit from taking simple precautions.
Steps customers can take to reduce fraud risks
- Never share a banking PIN, password or one-time verification code with anyone claiming to be a bank official.
- Verify suspicious requests using the bank’s independently confirmed official phone number or app.
- Enable transaction alerts and review account statements regularly.
- Avoid unfamiliar links requesting account details or urgent payments.
- Report unauthorised transactions to the bank immediately and keep the complaint reference and evidence.
These measures cannot eliminate bank-side security failures, but they can help customers identify suspicious activity earlier. Whether a disputed transaction is reimbursed depends on the facts, the bank’s investigation and applicable consumer-protection requirements.
Regulator urges stronger cyber resilience
In its stability assessment, the CBK emphasises strengthened cybersecurity, supervisory technology, financial-sector coordination and regulatory safeguards as digital finance expands. The figures show why preventing fraud—and rapidly containing losses after an incident—remains a significant priority for Kenya’s banks.
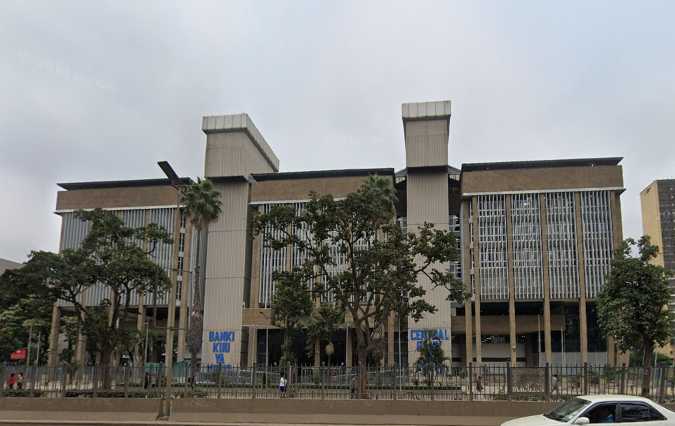
Featured photograph: Central Bank of Kenya headquarters in Nairobi. Photo by Abrahamns / Wikimedia Commons, licensed under CC BY 4.0. Unmodified image; shown for illustration.
Primary source: Central Bank of Kenya, Kenya Financial Sector Stability Report 2025 (November 2026 release), page 78, Table 14.
